
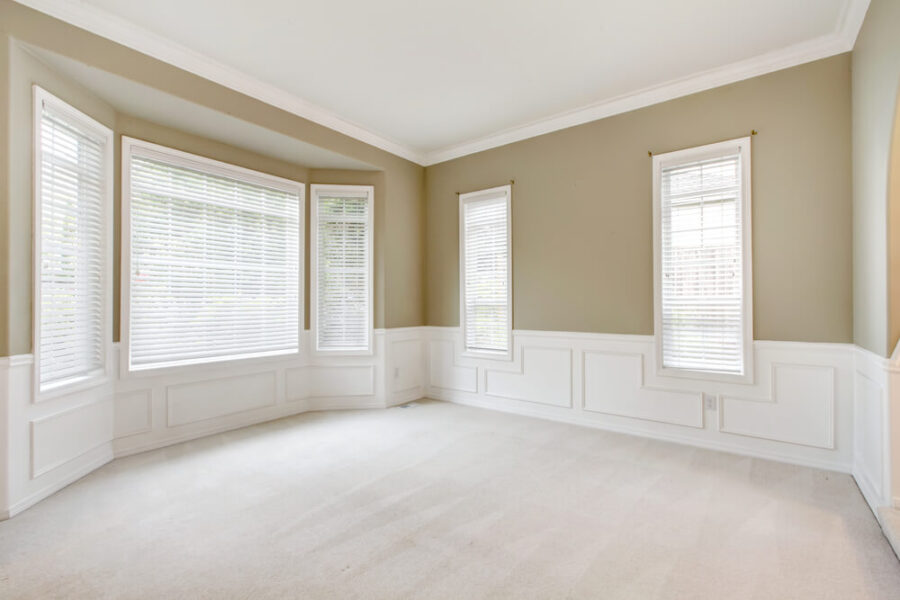
Living, monitored, and regularly used homes are the focus of standard house insurance. Once a home is vacant, the risk profile changes drastically. This shift is why regular coverage is typically unsuitable for an empty house and why empty house insurance is so popular. Even well-intentioned homeowners find too late that their insurance was never meant to cover the risks of vacancy, especially when the building is empty, systems are dormant, and risk-reducing routines are gone.
The problem is that insurers price policies on assumptions. Standard property insurance implies an owner or occupier is present, regular maintenance, normal heating and alarm use, and prompt damage detection. If a property is empty, those assumptions fail. It may take longer to notice water leaks. Damp can grow undetected. Security systems may malfunction or be turned off. Cold weather or strong storms can turn hours of damage into days of loss in an occupied property. The risk “story” changes, and traditional cover may not follow.
Vacancy-related exclusions or limitations are a common reason normal policies fail for unoccupied properties. Many common regulations specify “occupied,” “unoccupied,” and what happens after a certain period without a resident. The same definition can catch you even if you manage the building. If you start renovations, move, or own the property but cannot live there, your insurer may still consider it empty. In some cases, the policy may decrease or deny coverage for specific claims. The main reason individuals seek empty house insurance is that it accounts for vacancy, not just extends an occupied-house policy.
How standard insurance handles maintenance is another real issue. Life in a home has natural checks. Unusual scents, sounds, or leaks are noticed. They keep pipes from freezing. They maintain the property clean, preventing wetness and weeds. The “automatic safeguards” are gone in an empty house. Even if you inspect the property often, you’re not there daily. Reduced oversight may not be acceptable to standard insurance. Empty house insurance requires frequent inspections, water system protection, and security measures.
Water escape is a major concern. Temperature variations can cause pipes to freeze, rupture, or leak without warning. Homeowners may notice condensation, leaking, or a moist area before a leak develops. Moisture can hide behind skirting boards or in the building fabric in an empty house. If the leak persists, mould may grow within. Standard insurance may exclude unoccupied claims or need specific actions to meet. Empty house insurance is more likely to cover these vacant hazards, preventing a “no cover” claim.
Fire danger is another area where traditional policies fail. Vandalism, arson, and accidental ignition can target vacant properties. Reduced human presence can slow incident detection, even if the structure is secure. A fire that starts behind a door or in a loft can take longer to notice, and sprinkler systems may depend on water pressure, heating settings, and electrical integrity. Standard cover may not account for detection delay or have tougher vacancy requirements. Empty house insurance accounts for unoccupied firefighting response, detection delays, and risk.
Security differs too. Most home insurance assumes occupants lock doors and windows, respond to alarms, and keep keys in control. Security shifts when a property is unoccupied. Intruders may feel free to act, increasing burglary risk and damage. Even in well-maintained homes, an unoccupied property can invite vandalism if it appears neglected. Empty house insurance may involve monitored alarms, tight door and window locks, or access restrictions to address theft, attempted theft, and intentional damage claims.
Storm and weather damage might worsen during vacancy. Many homeowners believe that storm damage is damage regardless of occupancy. Damage can vary depending on how quickly problems are identified. A roof leak may start slowly under heavy rain. If someone lives there, wet stains may appear early. Water can soak insulation and damage electrics via ceilings when no one is home. Some standard policies require immediate discovery and may restrict coverage if the residence is not examined regularly during vacancy. Empty house insurance covers the eventuality of a property being left empty, with terms that better reflect delayed detection.
Also consider gradual decline. Regular living helps slow the difficulties caused by vacancy. Different heating patterns, ventilation, and humidity can cause mould. Wood may dry out and distort. Without inspection, electrical systems may represent hidden threats. Standard home insurance may prioritise quick, unintentional incidents above gradual deterioration in an unattended property. Empty house insurance emphasises upkeep and inspections and may better reflect the long-term dangers of an empty building.
Owners are frustrated when they submit a claim and learn the policy’s vacancy terms weren’t met. Time can be an issue: the property may have been empty longer than allowed. Other times, the insurance may need proof of frequent checks, heating maintenance, or protective measures. Standard policies often require compliance with criteria that are easy in occupied homes but difficult in vacant homes. Claims can be challenged. By tailoring your empty house insurance to the empty period and its requirements, you can lessen that risk.
What “standard” means across property kinds is another issue. A brick-built house with a secure fence, used occasionally but maintained, is simple. Some are more complicated: listed buildings, peculiar heating systems, annexes, or outbuildings. Building complexity increases the likelihood that basic cover will not adequately cover vacancy risk. When suited to how the property is used during the unoccupied period, empty house insurance can be more practical.
Handling many threats in an empty house is another gap. A break-in can cause theft and damage, which can lead to water entry if windows or doors are damaged. A modest heating failure might cause frozen pipes, water leakage, and damp damage. Standard policies may cover specific dangers but deny claims for vacant conditions. Empty house insurance is meant to reflect how these hazards interact during vacancy, making it more probable that the claim will be examined rather than dismissed for technical issues.
Policy phrasing can be quite precise, and how it defines “unoccupied” versus “occupied” can be crucial. Owners sometimes think they can treat a property as occupied by visiting sometimes. Based on how often someone is there, whether the home is still inhabited in, and if it is regularly maintained, insurers may disagree. The definition of occupation may be violated by “visits” alone. Empty house insurance removes that ambiguity by covering the fact that the house is empty and will stay empty.
This discrepancy is real financially. Many underestimate the cost of vacant property repairs following an incident. Water leaks can damage plaster, flooring, and mould remediation. Smoke can spread after a fire. Besides security costs, theft or vandalism can require structural and electrical repairs. When conventional cover does not apply, the owner may face a significant expense during a stressful and time-consuming disruption. Empty house insurance protects you from “normal cover” becoming “no cover” when it matters most.
None of this implies ordinary insurance is pointless. A normal inhabited household may find it suitable. The key is appropriateness. Standard regulations for active properties include monitoring and frequent checks. An unoccupied house has less oversight, modified weather exposure, increased vulnerability to malicious activities, and a higher chance of harm being discovered after it has spread. Empty house insurance arises because vacancy protection demands are different from daily living needs.
Choosing empty house insurance does not eliminate prudent safeguards. Policies often require written precautions such maintaining security systems, utilities, access control, and property inspections at predetermined intervals. These strategies often reduce claims and improve outcomes, not burdens. Empty house insurance aligns precautions with the policy’s goal. By matching vacancy risk, your policy is more likely to respond fairly if you need to claim.
Consider risk matching rather than legal theatre when insuring an empty period. What will happen when the property is vacant and how quickly will problems be found? Winter circumstances, security features, vandalism, water systems and their management, and a realistic maintenance plan should be considered. Compare that reality to policy assumptions. Most often, empty house insurance becomes increasingly significant as the scenario deviates from typical occupation.
Standard property insurance is unsuitable for unoccupied houses because vacancy alters risk kind, likelihood, and scale. Typical coverage assumes occupancy, frequent monitoring, and quick damage identification. During vacancy, the assumptions collapse, and the policy may exclude, reduce cover, or impose harsh conditions. Water escape, fire, security incidents, storm damage, slow deterioration, and delayed discovery create unique risk profiles that traditional insurance struggle to address. Unlike other insurance policies, empty house insurance is tailored to the behaviour and occurrences of an empty home to identify issues early.